The credit card surcharge ban has created some challenges for small businesses in managing payment costs while keeping prices competitive, customers happy and their business profitable.
As of 1 October 2026, following a Reserve Bank of Australia decision, businesses are no longer able to pass on credit card surcharges for Visa, Mastercard or EFTPOS payments.
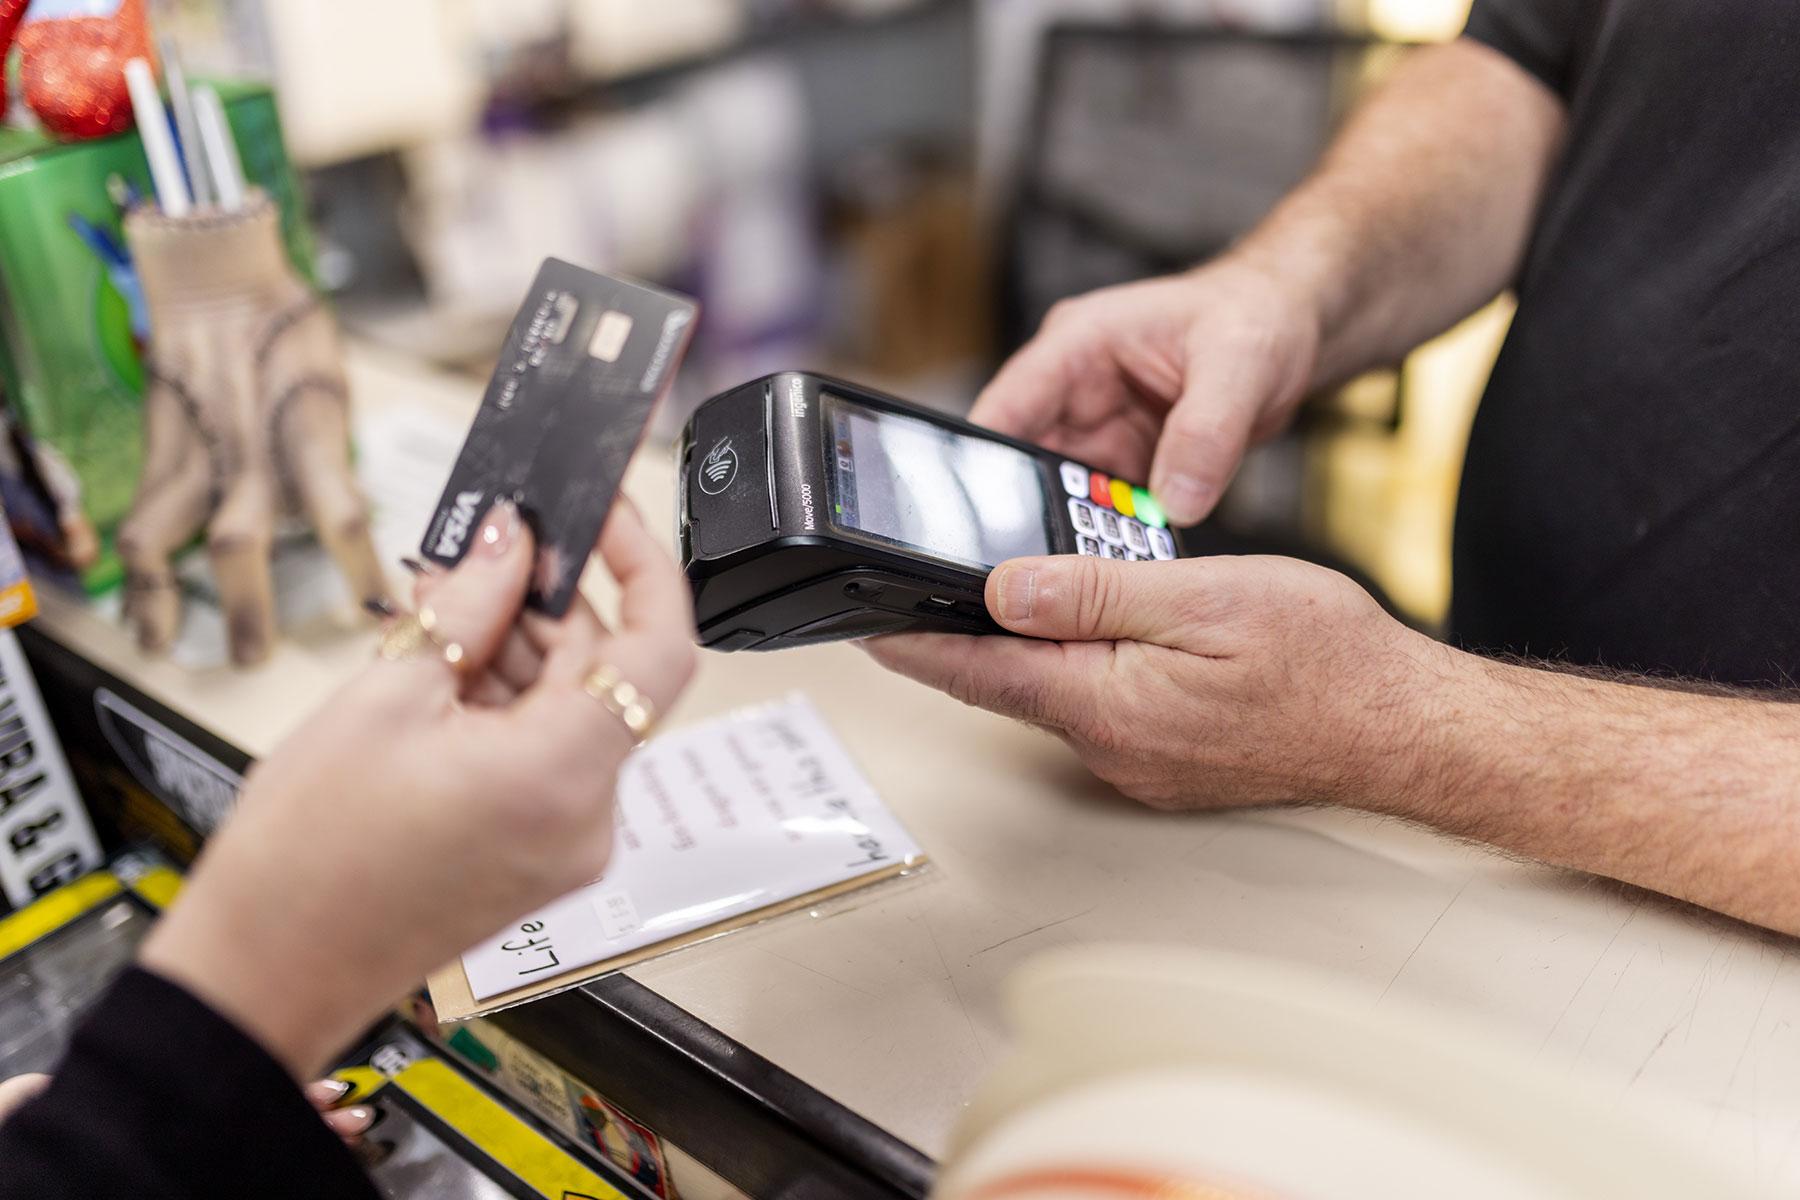
For many Australians, paying by card is a popular and convenient way to shop, whether they’re buying in-store or online. For small businesses, however, accepting card payments comes with costs. Businesses still need to pay merchant fees to banks or payment providers to accept Visa, Mastercard and EFTPOS payments, but will not be able to pass these costs on to customers through a surcharge.
One strategy small businesses can explore to manage the cost of surcharges is to make sure your bank or acquirer (the financial institution that processes transactions on behalf of a merchant) is offering you the right pricing for card payments. We spoke to one of the SBDC’s experienced business advisers, Steve McLaren, who has over 30 years banking experience. Steve provided a three step guide to help small business owners get the best deal from their credit card merchant.
Step one: Know your numbers
Now is a crucial time to really understand what you’re paying, including all the associated fees.
“Look beyond the headline transaction rate and consider the terminal rate, monthly account fees, gateway charges, minimum monthly fees, and other costs,” Steve says.
The best way to do this is to look at past statements (if possible, up to 12 months) and work out the total amount you’re paying your merchant each year.
Step two: Negotiate. You have power too
“You don’t necessarily need to switch to get a better rate. Your existing provider may be willing to offer a more competitive deal.”
Once you know your numbers, contact competitor merchants to ask what rate they can offer you, based on your turnover and current yearly costs.
If they offer better rates, ask your current bank or provider to review your rates, explaining how their fees compare with other offerings. Gaining multiple competitor quotes makes your argument more compelling.
Steve points out, “Remember, you have negotiating power. If you are a successful business, you contribute to your provider’s bottom line, and they’ll want to retain your custom.”
Step three: Carefully review your options
Take time to review your options - the cheapest option isn’t necessarily the best value if payments fail, settlements are delayed or support is hard to reach.
Consider if the payment solution matches your business:
- Do you take more payments in-store, online or by mobile?
- Do you accept international cards?
- What accounting, inventory or point-of-sale systems do you use, can the provider integrate?
“Make the best decision for your business right now and then review it regularly,” emphasises Steve.
“Your business changes and so can the market. As your sales volume grows you may become eligible for better pricing – so set annual reminders to review your rates.”
Final tips
- If you decide to switch provider, before you sign, consider setup fees, terminal rental or purchase costs, terms and conditions and other fees such as early termination or support charges in your total costs.
- Check whether rates are fixed or variable.
- Understand your transaction mix – if variable, your costs may fluctuate depending on the types of cards customers use, the value and number of transactions, and whether you accept domestic or international cards.
More information
Read more about the ban on surcharges for debit, credit, and prepaid card payments.
If you’d like to discuss pricing strategies or an issue facing your business, book an appointment with our free business advisory service.
You might also like to try our range of tools for your business, including cashflow forecasts and cost of goods sold calculator or explore our range of low cost financial management workshops.